Bright: Loans & Credit Builder

Screenshots
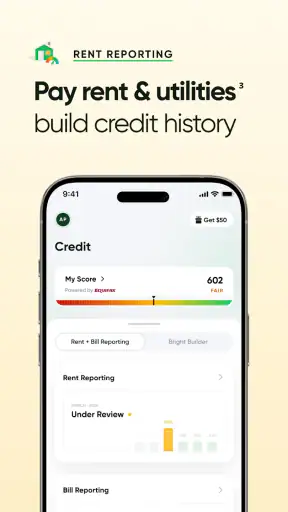
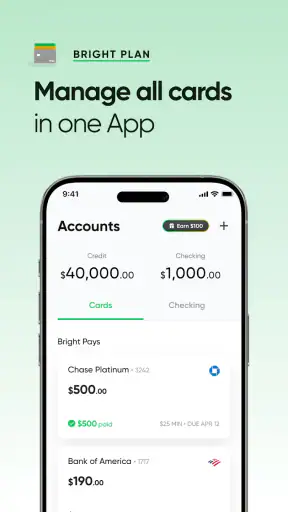
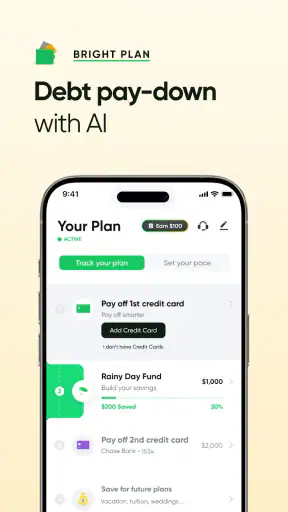
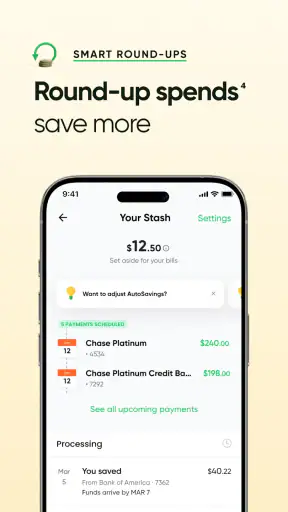
Details
- Rating
- 15.21K reviews
- Version
- 1.61.1
- Developer
- Bright Money
Analysis by Norviv
Bright: Loans & Credit Builder is a finance app from Bright Money that I would describe as a guided starting point for people trying to understand borrowing and improve their credit habits. I approached it less like a quick loan button and more like a financial assistant that needs careful reading. That distinction matters: borrowing decisions are serious, and an app can make the process feel simpler without making the underlying cost or eligibility disappear.
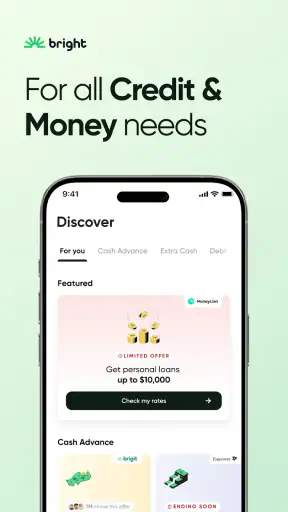
After spending time with the app’s purpose and presentation, my strongest impression is that it tries to bring several related tasks into one place: credit-building guidance, loan discovery, and access to credit-card options. It is free to install, aimed at Everyone, and available on Android devices running version 8.0 or later. Bright Money is the developer, and the app has reached over one million installs with an average rating of 4.6 from around 165 thousand ratings. Those figures suggest that it has found a substantial audience, although popularity should not replace personal checking when money is involved.
How Bright feels to use in everyday financial situations
I find Bright most useful when I treat its guided credit-and-borrowing focus as a way to organize a decision, not make one for me. In everyday use, that means naming the goal before exploring options and keeping a simple written comparison nearby. The next section looks at how that habit can make a financial app feel more practical—and less likely to rush me into a choice.
Readability and navigation for a money-focused app
The most important accessibility question here is not simply whether screens look clean. It is whether a person can understand what they are being asked to do before accepting a financial product. Bright’s central idea is easier to grasp than a traditional bank website filled with separate menus: the app presents itself as an AI loan assistant connected to credit-building and credit-card discovery. That focused purpose can reduce the effort of figuring out where to begin.
I found that this kind of guided approach can be helpful for someone who feels overwhelmed by financial terminology. Instead of starting with a long list of unrelated banking tools, you can think through a more specific goal: build credit, explore borrowing, or look for a card. For a first-time borrower, that framing is less intimidating than opening a general banking app and trying to interpret every available product at once.
There is also a trade-off. A guided flow may be easier to follow, but it can encourage people to move forward before they have compared every detail. I would slow down at each stage and look for the total repayment amount, recurring obligations, eligibility conditions, and any wording about credit checks. The app’s convenience is most useful when it organizes your questions rather than replacing them.
For readability, I would treat every financial explanation as something worth revisiting. People with dyslexia, attention difficulties, limited financial experience, or simply a stressful month may need to read an offer more than once. Bright can be a useful first pass, but I would not make a final decision while distracted, tired, or rushing through a phone notification.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Motor and sensory considerations while completing financial tasks
Finance apps are often used with one hand, on small screens, and in situations where a user may be carrying groceries, commuting, or dealing with a child. That makes simple movement and clear focus important. Bright’s value is strongest when its guided experience reduces the number of places a user has to search. Fewer decisions about where to go can be easier for people with limited dexterity or reduced concentration.
At the same time, I would not assume that a streamlined financial flow works equally well for every person. Anyone who relies on larger text, screen magnification, a screen reader, voice control, reduced motion, or strong contrast should test the app personally on their device. The practical question is whether labels remain understandable when enlarged, whether focus moves in a sensible order, and whether important explanations are announced clearly by the chosen assistive technology.
My advice is to complete the early exploration before entering sensitive information. That gives you a chance to see whether buttons, forms, and explanations are comfortable to use without feeling pressured to finish. If a screen becomes difficult to read or operate, switching to a larger display or asking a trusted person to review the wording can be safer than guessing.
Sensory context matters too. A bright, noisy room, a weak internet connection, or a phone with a cracked screen can make financial details harder to process. I would use Bright somewhere calm, with notifications paused, and keep a note of questions that arise. This is not just an accessibility preference; it is a good safeguard against agreeing to something because the surrounding situation makes careful attention difficult.
Situational access: who may benefit from the app
A realistic use case would be a person who has recently moved, has little experience with credit, and wants to understand the next step without visiting several separate websites. They might open Bright in the evening, identify whether credit-building or borrowing is their immediate priority, and use the guided information to create a checklist for comparing options. In that situation, the app’s focused purpose could save time and reduce the anxiety of starting from a blank page.
It may also suit someone who wants a single place to begin researching loans and credit cards rather than searching randomly online. The key word is “begin.” I would use the app to organize possibilities, then compare the details with the lender or card issuer directly before accepting anything. That workflow protects users who have difficulty holding several financial conditions in memory at once.
Bright is less suitable for a person who already has a detailed budgeting system and wants full control over every account, category, and transaction. A conventional banking app or dedicated budgeting tool may be better for day-to-day cash-flow management. Likewise, someone seeking emergency money should not assume that seeing a borrowing option means approval, affordability, or a good deal. The app can help explore a path, but it cannot remove the need to judge whether repayment fits the household budget.
For users with limited data access or older phones, the device requirement is relatively approachable because Android 8.0 and later is supported. Still, operating-system compatibility is only one part of access. A person may have an older display, limited storage, poor connectivity, or difficulty receiving verification messages. I would check that the phone is stable and that the user has enough time to complete any identity or application steps without interruption.
What the current version and audience tell me
The current version is 1.61.1, and the app has been available since August 31, 2020. That history gives Bright Money time to refine a product aimed at a complicated area of personal finance. It also means I would keep the app updated when possible, especially for a finance tool where reliability and compatibility matter.
The Everyone content rating makes the app broadly approachable in terms of age classification, but it should not be read as a promise that every financial product is appropriate for every user. Younger people or anyone new to borrowing may still need an adult, counselor, or financially experienced friend to help interpret the consequences. “Everyone” describes the intended content audience, not a guarantee of financial readiness.
The free price is another reason the app may be easy to try. However, free access to an app is not the same as free borrowing. I would separate the cost of using the software from the terms of any loan, card, or credit-related service presented inside it. Before moving ahead, write down the amount received, the amount repaid, the schedule, and what happens if a payment is late. That small habit is one of the most useful ways to prevent a friendly interface from hiding a difficult commitment.
Remaining barriers and points where I would slow down
The largest barrier is financial language. Even when an app explains a product clearly, terms such as interest, fees, repayment period, credit inquiry, and utilization can still be confusing. Bright’s guided format may reduce the initial learning curve, but I would not rely on an automated assistant to decide what is affordable. Treat its suggestions as prompts for investigation, not personal financial advice.
A second barrier is cognitive load. Credit-building is gradual, while a loan decision can feel urgent. Combining those topics in one app may be convenient, but it can also blur two different goals. Building a stronger credit profile is not the same as borrowing money, and taking a loan solely to improve credit may be a poor choice if the payments strain your budget. I would choose the goal first, then consider whether the available path actually supports it.
Privacy and trust also deserve attention. Any finance app requires a user to think carefully about the information being requested and why it is needed. I would read the relevant explanations, use a secure device, avoid public Wi-Fi for sensitive steps, and never share login codes with another person. These are sensible precautions whether the user has a disability, is helping a family member, or is simply unfamiliar with financial apps.
There is a practical accessibility issue for shared decision-making as well. A user with low vision, limited English proficiency, memory difficulties, or another support need may want a trusted person to review an offer. That can be helpful, but the account holder should keep control of passwords and verification codes. A good support arrangement means discussing the information together, not handing over complete access.
I would also avoid using the app during a crisis unless I had already decided what repayment could look like. When rent, medical costs, or utility bills are pressing, an attractive “get money” pathway can feel like the only answer. In that context, a nonprofit credit counselor, local assistance service, or direct conversation with creditors may be a better first step. Bright can be useful for research, but it should not be treated as an emergency safety net.
How it compares with ordinary alternatives
Compared with visiting individual lender websites, Bright offers a more concentrated starting point. That is its clearest advantage for me: the app’s identity connects the questions people often ask together, namely how to approach credit, whether borrowing is available, and where card options fit. A lender’s own app may provide more direct account servicing once you already have a relationship, but it may not be as helpful for someone still deciding where to begin.
Compared with a traditional bank app, Bright is more narrowly focused on credit-related discovery and assistance. A bank app is usually stronger for balances, transfers, deposits, and established accounts. Bright is not the replacement I would choose for those everyday banking tasks. I see it as an additional research tool rather than a complete financial home.
Compared with a spreadsheet or budgeting app, Bright addresses a different problem. A spreadsheet gives maximum control over income, bills, and repayment scenarios, while Bright can make the first exploration of credit products feel more guided. My preferred combination would be to use Bright for orientation and a simple budget outside the app to test affordability. If the numbers do not work in the budget, a polished recommendation should not change that conclusion.
Small habits that make the experience safer and more inclusive
First, decide what success means before opening the app. “I want to understand credit-building” is safer than “I need to accept whatever appears.” This prevents the interface from defining the goal for you and helps users with attention or memory challenges stay oriented.
Second, keep a plain-language record of every option you consider. Note the payment amount, timing, total cost, and questions that remain. A written comparison is especially useful for anyone who processes information slowly or needs to discuss the choice with a support person. It also makes competing offers easier to compare than relying on memory.
Third, use a two-pass workflow. On the first pass, learn what Bright is offering and stop before committing. On the second, check affordability, read the conditions again, and compare with a direct provider or another reputable source. This is a non-obvious but important trade-off: the app can save research time, yet rushing through its convenience can cost more than the time saved.
Finally, treat credit-building as a long-term behavior rather than a quick score shortcut. If a proposed payment would make essentials harder to cover, the right choice may be to wait, seek guidance, or work on a simpler plan. Bright is most helpful when it supports deliberate decisions instead of turning financial pressure into an immediate application.
My inclusive verdict on Bright
Bright: Loans & Credit Builder is a worthwhile option for people who want a guided introduction to credit-building, loans, and credit-card discovery in one finance app. I like its focused purpose, free entry point, and potential to reduce the confusion of starting research across many separate services. Its broad audience and long availability also make it feel approachable for someone who is not already comfortable with financial technology.
My recommendation comes with a clear condition: use it as an organized assistant, not as a substitute for reading, budgeting, or independent judgment. People who need detailed money management, direct bank servicing, or highly personalized accessibility controls may prefer other tools. Users with reading, motor, sensory, or cognitive needs should test the actual screens on their own device and involve a trusted support person when helpful.
In my view, the app earns its place when it helps a user ask better questions and compare choices calmly. It is not the right answer for every borrowing situation, and it should never make urgency feel like approval. Used slowly, with a written affordability check and attention to the terms, it can be a practical first step for someone trying to make credit less intimidating.
Frequently Asked Questions
01What is Bright: Loans & Credit Builder, and how does it work?
Bright is a personal finance app designed to help users manage debt, build credit, and organize repayments. After connecting eligible financial accounts, the app may analyze your financial situation and suggest a repayment strategy. Depending on your eligibility and location, Bright can offer credit-building tools, budgeting features, or access to loan-related services. Available products and terms may vary, so review the details carefully before accepting anything.
02Can Bright help improve my credit score?
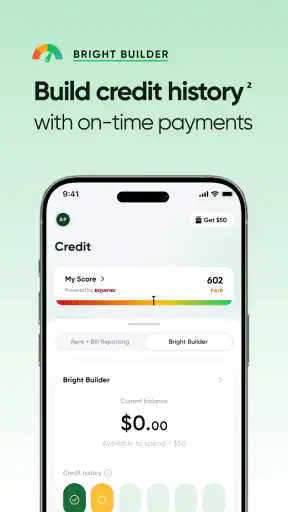
Bright may help support credit improvement by encouraging regular payments, organizing debt repayment, and offering tools intended to build positive financial habits. However, downloading or using the app does not guarantee a higher credit score. Your results depend on factors such as payment history, credit utilization, existing debts, and information reported by lenders. Always confirm whether a specific Bright service reports activity to credit bureaus before relying on it.
03Does Bright provide loans directly, and what are the costs?
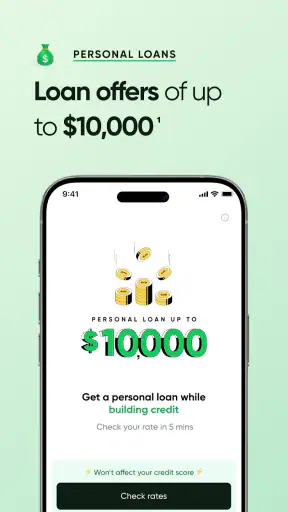
Bright may provide access to financial products or connect users with lending-related services, but the exact arrangement depends on your eligibility and location. Interest rates, origination fees, subscription charges, repayment periods, and other costs can differ significantly. Before proceeding, read the full offer, annual percentage rate, payment schedule, and cancellation terms. Never assume that an advertised loan amount or rate is guaranteed for every applicant.
04Is Bright safe to use with my financial information?
Bright may request access to personal and financial information so it can provide account analysis, repayment recommendations, or other services. Before linking an account, check the app’s privacy policy, permissions, security explanations, and the identity of any third-party providers involved. Use a strong password and enable available security features. You should also understand how your data may be stored, shared, or used for eligibility and personalization.
05Who can use Bright, and are there important eligibility requirements?
Eligibility for Bright’s features can depend on factors such as age, residency, income, bank-account access, credit profile, and the financial products available in your region. Some services may require a recurring subscription or a successfully linked account, while loan-related offers can involve additional underwriting. Because requirements and availability may change, review the current terms in the app and confirm that the service is offered where you live before downloading.


